
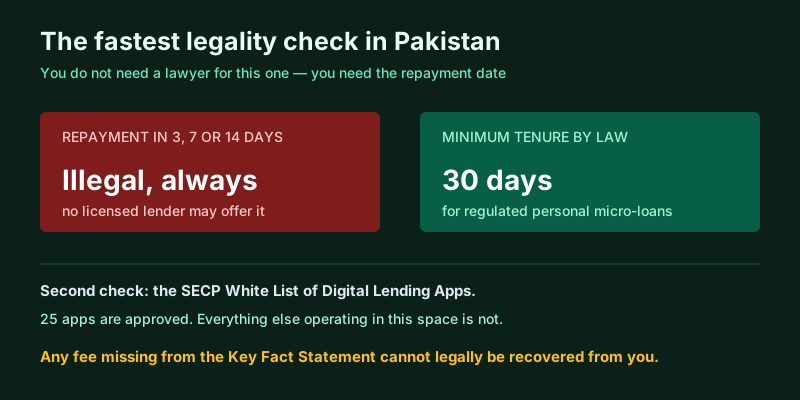
PLONLINE-PK-20260908There is a one-second test for any lending app in Pakistan, and it needs no legal knowledge: look at the repayment date. Regulated personal micro-loans are legally required to run for a minimum of 30 days. A 3-day, 7-day or 14-day repayment cycle is not aggressive pricing — it is illegal by definition, and no licensed lender is permitted to offer it.
The second check takes a minute. The SECP publishes a White List of Digital Lending Apps on its own website, and it currently contains 25 approved apps: 14 nano-lending and buy-now-pay-later platforms plus 11 others covering B2B, B2C, education finance and earned wage access. Anything outside that list operating in this space is not licensed, whatever its advertising says.
What enforcement actually looks like
These are not dormant rules. On 14 February 2024 the SECP blocked 132 illegal personal loan apps in a coordinated campaign with Google, Apple, the PTA and the FIA. On 22 May 2025 it blocked a further 141 unauthorised apps, noting that illegal operators had shifted to sponsored advertising on social media. Google has removed 84 apps reported directly by the SECP, and a further 93 flagged apps in early 2026 following technical compliance disclosures.
The perimeter is also enforced from the banking side: conventional banks, microfinance banks and payment providers are prohibited from extending wallets, payment gateways, deposit facilities, API integrations or credit-bureau checks to unlicensed lending platforms. An NBFC that collaborates with or facilitates an unauthorised app faces penalties of up to Rs. 50 million or cancellation of its licence.
What a licensed lender must tell you before disbursement
Before any money moves, a licensed lender must give you a Key Fact Statement covering the approved loan amount, the annual percentage rate or annual profit rate, the tenor, the repayment instalments or lump sum with exact payment dates, and every applicable fee — processing, service, verification, handling and late-payment penalties. It must be delivered in both English and Urdu, by video, audio, screenshot, email or SMS.
Then comes the clause worth memorising: any fee or charge not explicitly disclosed in that Key Fact Statement is legally barred and cannot be recovered from you. If a charge appears at repayment that was never in the KFS, you are not looking at a term you missed — you are looking at something the lender cannot collect.
What no licensed lender may do
- Touch your contacts or gallery — even with your consent. Access to the phone book, contact list and photo gallery is prohibited outright, and consent does not cure it. External storage, media images, SMS logs and fine location are equally off limits.
- Contact people in your phone. The only exception is a third party who explicitly agreed to act as guarantor at the time of approval.
- Coerce you. Threats of violence, abusive calls, fake legal notices, blackmail and morphed or edited photographs are all banned under fair collection standards.
- Lend for under 30 days. The minimum tenure applies to every regulated personal micro-loan.
If an app demands permissions to your contacts before it will even show you an offer, the request itself tells you it is not operating under these rules.
Borrowing from a bank instead: what is on offer
| Lender and product | Amount | Tenor |
|---|---|---|
| Askari Bank — personal loan | PKR 50.000 – 4.000.000 | 1–4 years |
| Pehchaan Finance — women-focused | PKR 50.000 – 3.000.000 | 1–4 years |
| The Bank of Punjab | PKR 50.000 – 2.000.000, up to 25× net monthly salary | 1–4 years |
| MCB Bank — unsecured | up to PKR 2.000.000 | up to 5 years |
| Meezan Bank — Consumer Ease (payroll partner) | PKR 35.000 – 1.000.000 | 3, 6, 12, 18 or 24 months |
| SECP-licensed nano apps | typically PKR 5.000 – 50.000; some to 100.000 or 200.000 | 1–6 months, minimum 30 days |
The Bank of Punjab ceiling is worth reading twice: the cap is not just PKR 2.000.000 but also 25 times your net monthly salary, whichever binds first. On a salary of PKR 60.000 that is PKR 1.500.000, well below the headline maximum. Most banks apply a multiple of this kind even when they publish only the absolute ceiling.
Fixed markup or KIBOR-linked?
Pricing comes in two shapes and the choice matters more than a percentage point at the outset. Bank Alfalah prices at 1-year KIBOR plus 18%, so the cost moves with the benchmark. Standard Chartered quotes a 38% flat rate, fixed but computed on the original amount rather than the declining balance.
The benchmark has been moving. The SBP raised its policy rate by 100 basis points to 11,50% in late April 2026, and KIBOR followed, climbing to 12,6% from 11,5% over May and June. On a KIBOR-linked loan that shift feeds straight into your instalment; on a flat-rate loan it does not, which is the argument for fixed pricing in a rising cycle — provided you have compared the two on total repayment rather than on the headline number.
What you actually need to apply
Applying through a bank’s own mobile app typically requires no physical documents, since the bank already holds your records. Through a branch or web portal you will usually be asked for a CNIC copy, recent salary slips, bank statements and proof of employment. The standard thresholds are a minimum monthly salary of PKR 25.000 to 40.000 and an age between 21 and 60.
If you are comparing against an app-based option first, our guide to instant personal loans covers what the fast route costs, and urgent borrowing looks at the same question when the timeline is measured in hours.
Before you tap apply
Run the two checks first: repayment date at least 30 days away, and the lender on the SECP White List. Then get the Key Fact Statement in writing and keep it, since it defines which charges can ever be collected from you. Ask whether the markup is flat or KIBOR-linked and request the total repayment figure both ways. And decline any app that wants your contacts or gallery — under Pakistani rules a licensed lender cannot ask for them at all, so the request is the answer.